COVID19 UPDATE: CDC Recommends Care Plans for Both Older Adults and Caregivers
Be Prepared - Have a Care Plan in Place

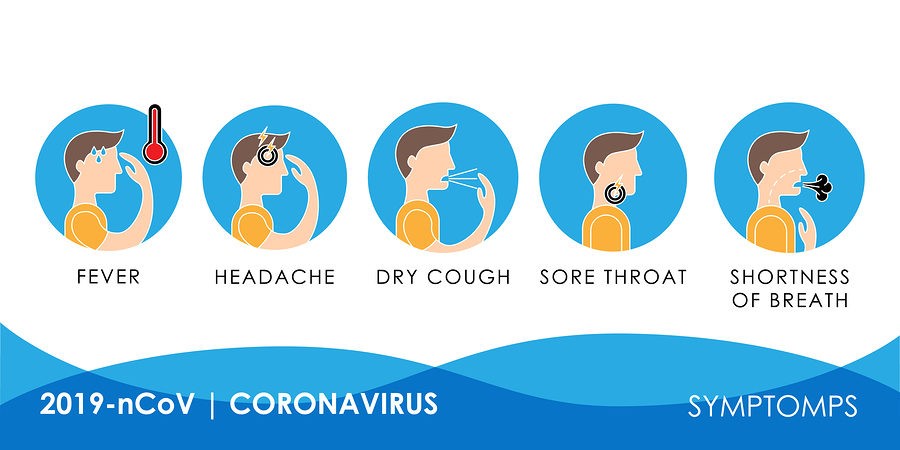
Quick. You or your senior loved one is running a fever, coughing and struggling to breathe. You suspect COVID-19 and a full-blown medical emergency starts to unfold. Medical professionals will need to quickly know the patient’s health conditions, medications, healthcare providers and emergency contacts.

Are you ready?

The Centers for Disease (CDC) recommends developing a Care Plan now as part of your emergency preparedness.

What is a Care Plan?

A care plan is a document that summarizes a person’s health conditions and current treatments for their care. The CDC offers a handy form you can use, Complete Care Plan. This is a fill-able form you can complete on your computer or print and complete by hand.

How Do You Develop a Care Plan?

The CDC offers these tips

  • Start a conversation about care planning with the person you take care of.
  • Talk to the doctor of the person you care for or another health care provider.
  • Ask about what care options are relevant to the person you care for.
  • Discuss any needs you have as a caregiver.

And remember, care plans can reduce emergency room visits, hospitalizations, and improve overall medical management, especially during a medical emergency.

For more information on Coronavirus issues that may affect you see https://galligan-law.com/covid-19-update-you-need-a-medical-power-of-attorney-now/ and https://galligan-law.com/coronavirus-scams-are-surfacing/.

Resource: Centers for Disease Control, Coronavirus Disease 2019, https://www.cdc.gov/coronavirus/2019-ncov/need-extra-precautions/older-adults.html

Suggested keywords: Develop a Care Plan, caring for the elderly, tips for caregivers, coronavirus caregiving tips, coronavirus and the elderly
Continue ReadingCOVID19 UPDATE: CDC Recommends Care Plans for Both Older Adults and Caregivers

Creating an End of Life Checklist

Creating an end of life checklist including assets, personal information and locations of important documents will help your family act on your behalf.

Spend the energy, effort, and time now to consider your wishes, collect information and, most importantly, get everything down on paper, says In Maricopa’s recent article entitled “Make an end-of-life checklist.”

The article says that a list of all your assets and critical personal information in an end of life checklist is a guarantee that nothing is forgotten, missed, or lost. Estate planning attorneys can assist you and guide you through the process.  Our firm prepares Estate Planning Binders which include schedules to hold that exact information.  As described here https://galligan-law.com/not-a-little-black-book-but-a-big-blue-estate-planning-binder/  Especially in the age of computers, it’s critical to leave this information for fiduciaries in a way they can find it.  They’ll be glad you did.

Admittedly, it’s an unpleasant subject and a topic that you don’t want to discuss, and it can be a final gift to your family and loved ones.

When you work with an experienced estate planning attorney, you can add any specific instructions you want to make that are not already a part of your will or other estate planning documentation. Make certain that you appoint an executor, one you trust, who will carry out your wishes.

This isn’t a complete list, but consider including the following personal information in your end of life checklist: your name, birthday, and Social Security number, as well as the location of key documents and items, birth certificate, Social Security card, military discharge paperwork (if applicable), medical directives, ID cards, medical insurance cards, house and car keys and details about your burial plot.  Your attorney will give you copies of your estate planning documents, such as your will, trust, documents relating to trust funding, powers of attorney, medical powers of attorney and so on.

In addition, you need to let your family know about the sources of your income. This type of information should include specifics about pensions, retirement accounts, 401(k), or you 403(b) plan.  Be sure to include company and contact, as well as the account number, date of payment, document location, and when/how received.

You also need to include all medicine and medical equipment used and the location of these items.

And then double check the locations of the following items: bank documents, titles and deeds, credit cards, tax returns, trust and power of attorney, mortgage and loan, personal documents, types of insurance – life, health, auto, home, etc. It’s wise to add account numbers and contact information.

Another area you may want to consider is creating a list of online passwords, in printed form, in a secure place for your family or loved ones to use to access and monitor accounts.

Be sure to keep your End of Life Checklist in a secure place, such as a safe or safety deposit box because it has sensitive and private information. Having it in one place will help your family when the time comes to act on your behalf.

Reference: In Maricopa (Feb. 14, 2020) “Make an end-of-life checklist”

Continue ReadingCreating an End of Life Checklist

Inherited Property? What You Need to Know

There are many options for what to do with inherited property, but they depend on debts, costs of property, beneficiaries and your needs.

Many clients wonder what to do with inherited property, particularly real property like a house.  There are choices, and they depend on several factors. Are there other siblings who also have inherited portions of the ownership of the house? Is there another owner who needs to be bought out? Can the heir afford to take on the responsibilities and expenses of a home? Is someone else already living there?  These are all questions presented in the article “What to do when inheriting a house” from The Mercury.

There’s a tax issue to consider, for starters. Property that was titled in the name of the decedent at the time of death or is part of their estate taxable estate and then inherited, receives what is called a “step-up” in basis. This means that there is no federal tax due on the appreciation in value from the time the person purchased the home to the time that the person died.  They may also be state taxes as well.

Let’s say the person bought the home for $100,000 and at the time of her death the property is worth $300,000. The federal government will not tax the $200,000 difference between the original value and the DOD (Day of Death) value of the home. If the heir obtains an appraisal shortly after the death of the home owner and then moves in or if you already live there and the house is transferred into your name, the “clock” starts running again for another tax break, which is an additional $250,000 exclusion from capital gains on resale after you have lived there for two years.  If the property is sold shortly after the person’s death to a third party in an arms-length deal, the sales price would be the DOD value of the inherited property.

Now, this all assumes that any other beneficiaries have been satisfied as to the ownership of the house. A good elder law estate attorney will be able to help with the details, including the transfer of title.

Another issue: is there a mortgage on the house? If so, the new owner may need to satisfy the lender and refinance. If the heir has enough money to meet monthly payments, a strong credit rating to be able to get a mortgage and enough income to maintain the home, then it should be a relatively simple transaction.

Have the home inspected before moving in. Is the inherited property in good shape? If repairs need to be done, are they budget-friendly, or will they make the inheritance too expensive to be financially viable?  Who will pay for it?  The estate, the heirs, or a new owner?

Property maintenance is another consideration. If the estate can carry costs associated with the property until the property is sold and if the estate can pay for repairs, upgrades and maintenance so the house can be sold for a good price, then that is a reasonable approach to take. If there are other beneficiaries, they should all part of a discussion about how much money is worth investing in the house and what the return on investment will be.

One key concern that I’ve told countless clients over the years is decide early what to do with the inherited property, and stick with the plan.  Maintaining the property is time consuming, potentially costly, carries a risk in the form of liability and may prevent the estate from making liquid distributions if it isn’t sold.  Some of the worst estate administrations I’ve dealt with involved not deciding what to do with inherited property, and that lead to unnecessary cost and years of administration. So, the executor or trustee should decide earlier what to do with the property.

Finally, if the language of the will says “equally to my three children” or language similar to that and one sibling wants to buy out the other two, then an agreement on the value of the house and a plan for working out timing of the sale will need to be created. An estate planning or elder law attorney will be able to help create a family settlement agreement that will include an informal accounting, whereby all of the heirs receive their fair share of the inheritance and all sign off that they have agreed to the transaction.

Reference: The Mercury (Jan. 15, 2020) “What to do when inheriting a house”

Continue ReadingInherited Property? What You Need to Know